Addition of VSTOXX Futures Data Page

To help bring greater visibility into the volatility landscape in Europe's stock market, we have added a page dedicated to VSTOXX Futures.

The VSTOXX index is the 30-day volatility index for the Euro STOXX-50 index, Europe's leading blue-chip index which provides a representation of the major sectors across 18 European countries.

Similar to our VIX Futures page, the VSTOXX Futures page contains quotes, historical volatility data, key metrics, and graphs that are useful in tracking volatility.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

Our VRP+VXX Bias Indicator +35% in 1st Quarter

The first quarter of 2015 has come to a close and investors everywhere are reviewing their performance. This is the perfect time to evaluate the effectiveness of your investment strategies and to make adjustments accordingly.

Our VXX Bias and VRP indicators have both navigated the first quarter quite well, at +31% and +29% YTD, respectively. These two indicators each provide end-of-day signals for placing swing trades in XIV and VXX (if you're not already familiar with our trading strategies you can learn more about them here). 

Our preferred strategy, VRP + VXX Bias, combines the two signals to place trades only when they agree on direction and is +35% YTD.

The graph below tracks the daily values for each of our indicators as well as XIV (buy-and-hold) as a comparison reference point (the usual investment benchmark, the S&P 500, is not included because it is an irrelevant +0.9% YTD).


We kept commission fees low by placing only a half dozen trades in the first quarter. Trade statistics for each strategy are summarized as follows**:


If you're not quite meeting your investment objectives this year perhaps we can help. For less than $3 per day we provide subscribers access to all of our VIX data & metrics, our indicators, automated Bias change alerts, and the members' forum.


--> New in 2015, we will be providing an additional level of visibility into our trading by having our performance verified by a third party (Marketfy). We recently tweeted our YTD portfolio performance of +17.8%, which was obtained by using the VRP+VXX Bias strategy as our guide. Look for additional updates on real-time notifications of our trades in the future.


**For those interested in additional detail, the daily history of indicator values that have been emailed to subscribers in 2015 can be found in the data sheet links below:
- VXX Bias: 2015
- VRP: 2015
- VRP+VXX Bias: 2015

______
Hypothetical and Simulated Performance Disclaimer
The results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown. Additional performance differences in backtests arise from the methodology of using the 4:00pm ET closing values for XIV, VXX, and ZIV as approximated trade prices for indicators that require VIX and VIX futures to settle at 4:15pm ET.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

Why (and exactly how much) Your Leveraged ETF Will Underperform

Experienced investors know that owning leveraged ETFs (2x and 3x) leads to decay in the value of the funds. The decay can be so strong that even if you get the direction right you may still end up with a loss. In this post I will quantify the decay on leveraged ETFs to illustrate the dangers of holding these funds.

As a brief bit of background, leveraged ETFs seek to return the 2x or 3x the daily return of the underlying security. Below are some examples:

NUGT: Returns 3x the daily return of Gold Miners ETF (GDX)
DUST: Returns -3x (inverse) the daily return of Gold Miners ETF (GDX)
TNA: Returns 3x the daily return of small cap stocks (IWM)
TZA: Returns -3x (inverse) the daily return of small cap stocks (IWM)
UVXY: Returns 2x the daily return of a blend of 1st and 2nd month VIX futures (VXX)


There is actually a known formula (**fellow math nerds can see the formula at the end of this post) for the return of a leveraged ETF. The critical variables that dictate leveraged ETF performance are:
1) The return of the underlying index (e.g. GDX, VXX, IWM)
2) The actual volatility of the underlying index
3) The amount of leverage (e.g. 1x, 2x, 3x)
4) The duration of the holding period


In quantifying the decay of these 2x and 3x ETFs I will start by mapping out #2, which is the actual volatility of the underlying index.

1) GDX: Actual volatility (HV20) range: 20 - 80


2) VXX: Actual volatility (HV20) range: 20 - 130


3) IWM: Actual volatility (HV20) range: 10 - 40


Using this information we can build tables and graphs to capture the various scenarios for the return of the underlying and compare that to the return of the leveraged ETF. (Note: All scenarios below assume a holding period of 3 months. Holding a fund for less than 3 months will see relatively less decay, while holding longer will experience greater decay.)

The return of the underlying index is listed in the first column while the various volatility rates are listed in the top row. The intersection of the index performance and its volatility rate gives the return of the leveraged ETF.

1) NUGT

For example, if GDX returned 5% over the holding period and had a 20% volatility rate, the return of NUGT would be 12.3%. Another scenario would be a holding period return in GDX of -12.5% and a volatility of 60%. This results in a return of -48.9% in NUGT. Note that cells colored red indicate that the leveraged ETF is underperforming 3x of the underlying index, while green cells are outperforming. It should be clear from the above that under most scenarios except for when actual volatility is low, a 3x fund will underperform.

The scenarios in graph above can be drawn in graph form for better understanding. The horizontal axis marks the return of the underlying index (GDX, IWM, etc) and the vertical axis marks the return of the leveraged ETF.

NUGT & TNA:

Leveraged inverse ETFs (DUST & TZA):


UVXY:
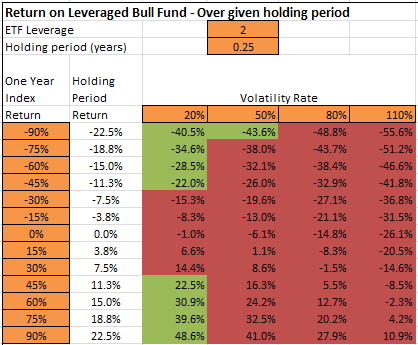
Because UVXY is only a 2x leveraged fund we a need different chart. However as shown above, the actual volatility of VXX is much higher as well which changes other input ranges.


The resulting concept is the same however: the higher the actual volatility of the underlying (VXX), the more UVXY will underperform. 

Consider someone who expect the market to crash while VIX spikes 80% and VXX spikes 60%. If the underlying volatility of VXX is 80% (which is likely to happen during market crash), UVXY only returns 12.7%. If VXX returned 80% but the actual volatility of VXX is 110% (it saw 120% in fall of 2011), the UVXY return is only -2.3%. Obviously UVXY is a very poor hedge to hold for any significant duration. It is really only beneficial for short duration trades if you have impeccable timing.

Here are the UVXY returns in graphical format:


Don't be lured by the potential return of these leveraged ETF products. Unless actual volatility of the underlying index is very low, you're likely to be just another victim of leveraged ETF decay.


_________
** Return (R) for a leveraged ETF is defined by:

Where x is the leverage ratio, σ is the volatility of the index, and T is the time period the investment is held (source Cheng and Madhavan (2009) and Wang (2009))


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

Utilizing Two Complementary Strategies to Trade VXX & XIV

In early December we made a second strategy for trading VXX and XIV available to our subscribers: the Volatility Risk Premium (VRP) strategy. You may remember me outlining the excellent performance of this strategy in my previous blog post, Volatility Strategies - Separating Fact From Fiction. I liked the strategy so much I decided to make a few adjustments and launch our own version of VRP to use along with our VXX Bias on our Daily Forecast page.

Why use two strategies for trading volatility ETPs? Because no single strategy is perfect and the market is inherently unpredictable. Using two complementary strategies simultaneously compensates for inherent weaknesses within each of the strategies, reduces drawdowns, and smooths out returns over months and years.


The VXX Bias and VRP strategies each take a very different approach for maximizing gains. The VXX Bias strategy is based on the term structure and momentum of VIX futures, while VRP is based on the price of VIX and historical volatility measurements. However, each of these strategies thrive and struggle depending on the specific market conditions. For example, the VXX Bias strategy has an advantage in handling periods of moderate drawdowns and sustained periods of backwardation. Meanwhile, the VRP strategy tends to be better with choppy markets and periods of gradually increasing volatility when VIX futures are in contango. 


You can see in the backtest results below that neither strategy consistently outperforms the other over a given year, although both VXX Bias and VRP are vastly superior to a buy-and-hold approach with XIV. 


As you can see in the chart above, using the VRP and VXX Bias strategies together (the green columns) provide more consistent returns than using just one strategy alone. In most years the "VRP + VXX Bias" strategy return falls roughly halfway between the VXX Bias and VRP strategies used on their own.  (Note: There are a couple ways to incorporate two strategies, but the easiest way is to trade in VXX or XIV only when they agree on the trade direction, which is how the above results are generated.)


Looking at the strategy statistics below, we see that the VRP + VXX Bias strategy benefits from a reduced maximum drawdown and a 0.90 Sharpe Ratio. 


Other relevant stats for trading only when VRP and VXX Bias agree on direction (years 2004-2014):

- # of trades: 191
- Avg hold time: 9.8 days
- # of days out of market in cash: 821 (out of 2711) --> 30%
- Avg trade return: 5.35%
- Max trade gain: 110.8%
- Max trade loss: -20.3%

The equity curve for each of the strategies (below) illustrates the smaller drawdowns and improved performance of using VRP and VXX Bias together:


Table of annual returns for the above data:


Full test data for both the VRP and VXX Bias strategies can be found in the spreadsheets at the bottom of the Subscribe page. You can also read more about our trading strategy on our Strategy page.

Access to our daily indicators and automated alerts for both the VRP and VXX Bias strategies is available via subscription to Trading Volatility+. 


------------
Hypothetical and Simulated Performance Disclaimer
The results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown. Additional performance differences in backtests arise from the methodology of using the 4:00pm ET closing values for XIV, VXX, and ZIV as approximated trade prices for indicators that require VIX and VIX futures to settle at 4:15pm ET.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

2015 CBOE Risk Management Conference - Attendees get 30% off Subscription to Trading Volatility+

CBOE's Risk Management Conference is the premier educational forum for users of volatility products and equity derivatives. It is *the* conference for financial professionals to attend to learn the latest risk management tools and tactics from top traders and strategists. 

The next CBOE Risk Management Conference is scheduled for March 4-6 in Carlsbad, California. The agenda is now set with talks from over two dozen industry experts, exploring the latest products, trading strategies and tactics used to manage risk exposure and enhance yields. The full agenda is available here.

As an added bonus, attendees at the March 4-6, 2015 session are able to get a 30% discount* on their first three months of a Trading Volatility+ subscription. 

Our Trading Volatility+ service provides access to:
  • Our full suite of volatility metrics and indicators to bring you valuable insight into the movement of VIX ETPs, 
  • Our strategies, which utilize variations on widely-used trading indicators (such as Volatility Risk Premium) as well as our own proprietary algorithms (VXX BiasTM and ZIV BiasTM),
  • Our automated alerts which notify subscribers whenever one of our indicators experiences a critical change in direction, making the strategies easy to follow,
  • Our members' forum where you can interact and share ideas with other volatility traders. 
The unique characteristics and profit potential of VIX futures led to the fifth consecutive annual trading volume record in 2014. 2015 is already looking to break that record again as interest in volatility as a tradable asset continues to grow. If you're still shying away from this well-kept secret of sophisticated investors, now is is the time to learn more. A good place to start is with our concise (and FREE!) e-book, Fundamental Concepts and Strategies for Trading Volatility ETPs.


*Discount available only to new subscribers. The discount will be refunded to subscribers after providing proof of event attendance.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.