The Quest To Outperform The Market

Chances are, if you're an active trader in this market you are struggling to make money. In reality it's a tough game, one in which hedge funds and mutual funds constantly underperform the market.  In 2012, 88% of hedge funds and 65% of mutual funds underperformed the S&P 500 benchmark. In 2013, the hedge fund average trailed the S&P 500 for the fifth straight year with a 7.4% return, 23 percentage points below the S&P 500.

Why do so many professionals and individual investors lose money? Because in order to be successful in trading you need both a good plan and the discipline to execute against the plan. Without both of these a trader will fail to make money consistently.

While we can't really help you with the discipline, we can help you with the plan. We focus most on trading two securities, VXX (the "volatility futures fund") and XIV (the "inverse volatility futures fund"), based on the direction of the fund's built-in Bias. The Bias is our proprietary way of measuring the current directional force on the fund and is primarily based on the price structure of VIX futures and the internal mechanisms that the funds use to manage their holdings. As these values change each day we measure and report on the Biases in our Daily Forecasts so that we know both their direction and magnitude.

With that information, we apply the simple strategy of buying XIV when the VXX Bias is negative, or buying VXX when the VXX Bias is positive. Trading in the direction of the Bias is critical since it can impact the price of the fund by as much as 10% per week. Trading in the direction of the Bias allows traders to take advantage of the funds structure and can provide an edge in trading.

Over the past couple years, XIV has become a popular fund to own with annual returns of 142% and 85% in 2012 and 2013, respectively. But this is not a fund to buy and hold since it is prone to 80%+ losses if the Bias reverses (see XIV: When a "Sure Thing" Goes Bad). You can see in the table below that while the average annual return of XIV is 46%*, it experienced several ugly years when there was an unfavorable Bias. Rather than suffer through these losses, XIV can be sold whenever the VXX Bias is positive to help reduce drawdowns. This "Negative VXX Bias" strategy has been shown to substantially outperform XIV in 6 of the past 8 years, with an average excess performance of 48 percentage points (far right column, below).


% Gain / Loss By Year
YearXIV"Negative VXX Bias" Strategy"Positive VXX Bias" StrategyExcess performance over XIV using "Negative VXX Bias"
200673%60%-15%-13%
2007-51%-34%13%17%
2008-71%-8%128%63%
2009103%116%-9%13%
2010135%284%42%149%
2011-47%45%61%92%
2012142%216%11%74%
201385%74%-30%-11%
Average46%94%25%48%


A look at each year's performance of the "Negative VXX Bias" strategy shows that while it is still vulnerable to losses, overall the strategy has done exceedingly well compared to the alternatives. A comparison of the annual returns of XIV vs the "Negative VXX Bias" strategy is better visualized below.


You can get a feel for how the strategy performs on a day-to-day basis by looking at the each of the performance data files (**links located at the bottom of this post). In these files you can view a graph of the daily value of a portfolio employing each strategy. The chart below compares the "Negative VXX Bias" strategy to XIV during 2011. Note the flat blue line which illustrates that XIV was not owned in the "Negative VXX Bias" strategy during the time XIV experienced steep losses because there was a positive VXX Bias.


The performance data files also contain the forecast VXX Bias values, entry and exit points, and gain/loss data including a histogram of trades. Below is a summary of trades each year for the "Negative VXX Bias" strategy.

Number Of Trades Per Year For Negative VXX Bias Strategy
Year# of TradesWinnersLosersAvg Trade Gain/Loss
200612664.94%
20071459-2.43%
20081376-0.33%
200911658.05%
201075323.34%
201110374.54%
2012115612.51%
201315874.27%


Given the size of gains & losses I've discussed so far it should be clear that these strategies typically align with traders who have a relatively high tolerance for risk. They are not for everyone and they are certainly not for anyone who does not pay attention to the changing Bias of the funds. However, if you're a trader who has decided that these types of funds are right for you, we would love to provide you with the tools to assist in your analysis and decision making process.

In addition to tracking these Biases on our website, we can also send email alerts to let subscribers know when the VXX Bias has changed direction. To learn more about the services we provide you can check out our Subscribe page, or drop us a line via the Contact page. You can also chat with us on Twitter at @tradevolatility if you like. We're here to help and answer any questions you might have about the world of volatility!


------------

*Daily prices for VXX and XIV prior to fund inception have been derived from existing VIX futures data. Backtests use each security's 4:00pm ET closing value as an approximated trade price for indicators that require VIX and VIX futures to settle at 4:15pm ET.

**Data files: 2006, 2007, 2008, 2009, 2010, 2011, 2012, 2013, 2014


------------
Hypothetical and Simulated Performance Disclaimer
The results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown. Additional performance differences in backtests arise from the methodology of using the 4:00pm ET closing values for XIV, VXX, and ZIV as an approximated trade prices for indicators that require VIX and VIX futures to settle at 4:15pm ET.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

VXX Bias Forecast Performance Review, 2014 Year-to-Date

With one third of 2014 now behind us, it's a good time to take a look at year-to-date performance of our Bias strategy. The U.S. stock market has been mixed so far this year (through May 9, 2014) with the S&P 500 index gaining 1.6%,  the Russell 2000 down 4.8%, and the NASDAQ 100 down 1%. The VIX has lost 5.8% YTD although it has seen some wild swings already, gaining 56.3% in early February before returning back to where it started.

At Trading Volatility we focus on trading of VIX ETPs with most attention on VXX and XIV. Today we'll review the year-to-date performance of the VXX Bias forecasts, which are generated after each trading day at 4:30pm ET.
- For those of you who are unfamiliar with our daily Bias forecasts more information can be found on the Daily Forecast page.
- For backtested performance of the Bias strategy dating back to 2006 please see this post.

VXX Bias Indicator Performance, 2014 YTD (Data sheet with trade and performance details)
As usual, we'll review the performance of the indicators in two halves:
1) the "Negative VXX Bias" strategy which involves buying XIV whenever the VXX Bias is negative, and
2) the "Positive VXX Bias" strategy which involves buying VXX whenever the VXX Bias is positive.

1) Negative VXX Bias Strategy
The VXX Bias forecasts are designed to help traders identify the direction and magnitude of any headwinds/tailwinds in VXX and XIV that arise from the structure and momentum of the underlying VIX futures securities. So far this year the Bias forecasts have identified a key change in market structure in early January to give traders a chance to exit positions in XIV before the full 29% drawdown (see graph below). Confident investors sparked a stock market rebound to keep that drawdown contained, but we've seen a mostly sideways/choppy market with a neutral VXX Bias for the majority of the year. Long-time readers of our posts will know that a neutral Bias makes for little or no trading edge in VIX ETPs, making for a more difficult trading environment. However, in late April & early May we've seen the VXX Bias grow more negative and exit the neutral zone to drive new lows in VXX and drive price higher in XIV.
- As of May 9, XIV has returned 0% YTD vs +3% with the Negative VXX Bias strategy.


2) Positive VXX Bias Strategy
We've seen several moves to a positive VXX Bias this year but only one instance has lasted more than a handful of days. In the January instance the VXX Bias remained positive for 13 days, with VXX gaining over 30% before finally closing out a 10.8% gain. Most of the remaining VXX trades have ended with small losses in typical VXX behavior. 2014 has once again demonstrated that while VXX can see good short-term gains, they tend to be fleeting when the Bias quickly returns to negative.


------------
Hypothetical and Simulated Performance Disclaimer
TThe results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown. Additional performance differences in backtests arise from the methodology of using the 4:00pm ET closing values for XIV, VXX, and ZIV as an approximated trade prices for indicators that require VIX and VIX futures to settle at 4:15pm ET.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

Say Hello To The New Uptrend In VIX And VIX Futures

Recap of the Week: 4/7/14 - 4/11/14
We saw a bit of weakness in the market last week with SPX down 3 of 5 days. VIX largely took the movement in stride, indicating that market participants continue to believe that dips will be bought, or at least, that this particular dip will be bought. We saw a signal to sell XIV / buy VXX on 4/10 as the VXX Bias and WRY MACD moved to positive on Thursday. The next day we saw VIX move as high as 17.85, before closing at 17.03 (+7%). This value of VIX is unusually low for a situation where SPX lost 3% over the course of 2 consecutive days (actual volatility for the week was 19.5). A VIX in the low/mid-20s would be more appropriate given historical comparisons (see this tweet after this Thursday's 2% sell off). No, the VIX is not "broken" here -- this just indicates that market participants do not see the need to buy puts to hedge their positions since the market has been in the pattern of quickly recovering from 5% dips in this new QE era.

Key Points & Outlook
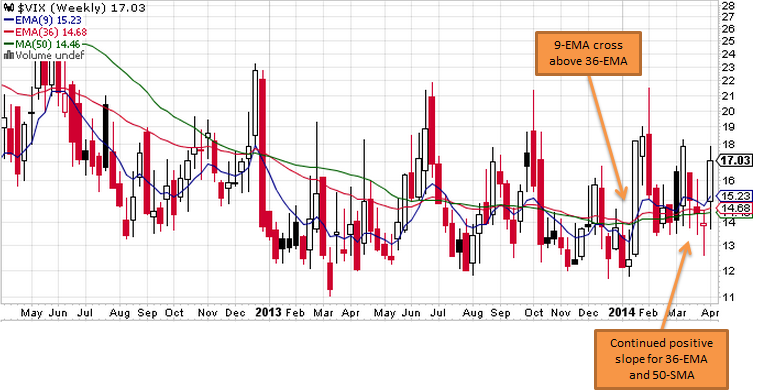
- After a false break lower the week of 3/31 - 4/4, VIX opened up higher this week, retraced to last week's close by Wednesday, then continued up to close at a 4-week high. This kept the longer-term uptrend that started the week of 1/21/14 intact. VIX weekly chart, below, shows the 9-ema rise above the 36-ema and test it twice so far. Also note the positive slope of the 36-EMA and 50-SMA.


- (Remaining Key Points & Outlook are available to Members only. Please login to the Members' Forum to read the remainder of this article. If you're not yet a member you can join via the Subscribe page.)
.
.


Major Shifts In Volatility Structure
We've watched many significant developments in the world of VIX and VIX futures unfold over the past two months and have been discussing these events and their implications in our Members' Forum. Below I've jotted down a summary of points from our recent posts to provide a glimpse of these conversations. 

(You can get access to the Trading Volatility Forum as well as our VIX Futures data and analytics for just $40/month. See the Subscribe page for details.)

2/24/14 - Theme: Rising actual volatility (HV20 & HV60) in the S&P 500 is a sign of an aging market and signifies shifting market sentiment.
- VIX has shown a bit of reservation over the latest two week rally.
- Do not expect XIV to behave in the same way in 2014 as it did in 2013; Expect choppy trading and weaker bounces like what we are seeing now. 

2/28/14  - Theme: Disappearance of the roll yield and a higher VIX base
- VXX Bias has narrowed -- almost no negative roll yield in VXX since early Feb
- VIX making higher lows, forming base in 14s
- Near-term VIX futures not selling off this time around. Trending up since Feb 18.
- Investors not selling VIX futures this time around

3/18/14  - Theme: Market Indecision and VIX Doubt In The Latest S&P Rally
- VXX Bias remains thinly negative
- VIX indicating lingering uncertainty despite S&P rally
- Continued rise in level of actual volatility in SPX, specifically HV60
- VIX/VXV bouncing above & below 0.92 threshold, indicating a high level of indecision

3/28/14  
- Continued indecision with VIX range-bound
- Watch for development of more negative VXX Bias

3/31/14 
- Break of the VXX trendline indicates lower prices to come

4/3/14 
- Weak market action in NDX and Russell 2000 prompts reduction in XIV position. Not a good time to aggressively short volatility.

4/4/14
- No show of fear yet despite selling in SPX. Watch out for further downside on Monday (4/7), 

4/10/14
- Change in VXX Bias and WRY MACD signal a move higher in VXX. 


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

Shorting Volatility: Time To Reduce Profit Expectations for 2014

With XIV down 7.6% so far this year after seeing 100%+ annual returns in both 2012 and 2013, many have been asking "Is the short volatility trade dead in 2014?" While my terse answer is "not necessarily," we need to take a closer look at the various aspects of the VIX futures market in order to gain some insight on where VIX ETFs could be headed.

The idea of reduced profit expectations for XIV is actually not new. Although XIV gained 107% in 2013, its gains have slowed to just +36% over the past 12 months. While we've talked about this several times last year (here and here and here), today we'll talk about why and take a look at the current outlook.


VIX Futures
The daily price movement of XIV/SVXY, VXX and UVXY/TVIX are determined by the price of the front two months of VIX futures. In the chart below you can see both front month (M1) and second month (M2) VIX futures over the past 12 months.


Current values of M1 (14.85) and M2 (15.75) are generally in the lower-middle portion of the range. We've seen these M1 & M2 price levels with a similar ~1 point spread before. In fact, M1 and M2 are essentially unchanged from 12 months ago and we've seen the same levels six other times during the past year (4/26, 7/29, 9/16, 10/30, 12/3, and 12/19). On all of these occasions we've seen M1 and M2 continue to fall, providing an average gain for XIV of 9% over the next 1-2 weeks. These gains tend to be short-lived as multi-day volatility spikes have resulted in 15%+ drawdowns in XIV for 5 of the 7 instances (exception were 10/30/13 and 12/3/13). This doesn't mean that the same thing will happen this time around, but it does provide some interesting data points.

We can see these moves reflected in the 1-year chart of XIV, below. While VIX futures are essentially unchanged over the past 12 months, monthly expiring futures and the roll yield continue to provide fuel for gains in XIV, which is +36% over the past 12 months (and VXX is -47%). There's no reason this dance can't continue at this "slower" rate as long as M1 and M2 remain range bound under 20, but periodic drawdowns are likely to continue resulting in choppy trading.


As a relevant side note, 3 month actual volatility in the S&P 500 (HV60) has risen about 1.3 points over the course of the past five months. This often serves as an approximate lower-bounds for VIX, as we can see in the HV-IV chart below (see green circles). This means VIX is less likely to soon push back down into the 11.9/12.3 range we saw late last year.


VXX Roll Yield
In addition to looking at the relative position of front month VIX futures, we need to also look at the headwind/tailwind for the securities that arises from the roll yield. The roll yield is proportional to the difference between the 1st and 2nd month VIX futures. Below I've charted VXX's weekly roll yield (WRY) over the past two years.


You can see how the roll yield for VXX has been much less negative so far this year, providing for less of a headwind for VXX and less of a tailwind for XIV/SVXY. In fact, so far this year the average VXX WRY has been just -0.7% (which is +0.7% for XIV). To put that number in context, below is a table of the average XIV weekly roll yield for each of the past 9 years.

XIV: Average Weekly Roll Yield vs. Annual Return
Year Avg WRY Annual Return
2005 1.6% 101%
2006 1.4% 14%
2007 0.6% -35%
2008 -0.6% -71%
2009 0.9% 118%
2010 2.1% 144%
2011 0.5% -46%
2012 2.1% 154%
2013 1.6% 107%
2014  0.7% -8% (YTD)


The 2014 average WRY is more or less in the middle of the range between the low (-0.6%) and high (+2.1%). So why is this important? Because the return of VIX ETFs is largely dependent on the roll yield. as illustrated by a scatter plot for the above table.


You can largely expect that the return of XIV 2014 will end up somewhere along this line. Think about this chart for another minute. Essentially the trendline is telling us that XIV needs an average WRY of at least 0.5% to have a chance at being positive for the year. Factor in a few 25%+ XIV drawdowns and realistically it needs an average WRY of 1% to really provide some confidence in the trade. With VIX futures already quite compressed along the entire term structure, that 1% WRY will be difficult to maintain unless M1 is able to spend much more time in the 13s. This would imply a VIX down in the 11-12 range -- quite a tall order at the moment.

Outliers on the graph above are the result of either a) major differences of the yearly starting and ending values of M1 (i.e. in 2009 M1 went from 45 to 20), or b) large multi-day volatility spikes that cause major (50%+) drawdowns in XIV (e.g. 2006, 2007, 2011) which are difficult to recover from based on the dynamics of percentages (i.e. it takes a 100% gain to fully recover from a 50% loss). For reference, below is a chart showing the value of front month VIX futures over the past 9 years (note that while M1 is low compared to the recent 5 years, it is still higher than most of 2005 and 2006).


VXX Forecast Review
As I turn to look at our daily VXX Bias Forecasts history, below, you can see why we identify the area between -1 and +1 as a "neutral zone" (highlighted in yellow) which is subject to a certain amount of thrash. These are are times when VXX generally moves sideways and is more susceptible to spikes. After looking at this forecast history it's not much of a surprise to learn that neither VXX (-1.7%) nor XIV (-7.6%) have gone anywhere this year.


Summarizing the current situation for XIV (and VXX/UVXY):
  • We've seen a narrow XIV weekly roll yield so far in 2014, but it has been increasing lately to the point where it is back above 1%. If XIV is going to continue to see gains the WRY needs to stay above this level. 
  • VIX futures are at the lower end of the range over the past few years. They've been at these levels and can continue lower, but their downside is more limited than the upside at this point, making for a pretty non-ideal time to aggressively short volatility. 
  • XIV has the potential to continue to rise as VIX futures roll forward each month. The next expiration date is April 16th.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.

VXX WRY-10SMA Indicator Updated -- Now the "WRY MACD" Indicator

In late December we introduced a new strategy for trading volatility ETPs which looked at the Weekly Roll Yield ("WRY") for VXX at the end of each day and subtracted it from its 10 day simple moving average. The strategy provides more frequent trading signals than the Bias forecast and can help traders better avoid short-term drawdowns of XIV.

Today I'm excited to announce that we've updated the strategy to reduce the amount of signal noise by utilizing exponential moving averages. The result is 30% fewer trades and substantially improved performance in our backtested performance. The new chart will be published daily at the same location on the VIX Futures Data page.

The original WRY-10SMA chart looked like this:


In the new methodology which utilizes the 5EMA and 8EMA of the VXX WRY, the chart looks like this:


As you can see it is a very similar graph, but the WRY moving average lines (blue and purple) are smoother to reduce false signals and choppy trading.

Since we only care about whether the 5EMA is above or below the 8EMA, we've taken the update one step further to help simplify the chart and make it easier to identify when the lines cross. We replaced the two EMA lines with one line, by taking 5EMA minus 8EMA (Note: This is essentially a variant on the standard MACD calculation). Left axis is the MACD signal, while the right axis is VXX price.


Trading Strategy
A positive WRY MACD crossover indicates short-term upward momentum acting on VXX. A negative WRY MACD crossover indicates indicates short-term downward momentum acting on VXX. Therefore, the strategy is to be short VXX (or long XIV/SVXY) when the MACD value is negative, and long VXX when the MACD is positive. The best results in a hypothetical portfolio are obtained by using the WRY MACD indicator along with our Bias forecasts to trade in the same direction of a VIX ETPs current bias. As noted in the announcement of the original version of this strategy (WRY-10SMA), gains from being long VXX when the bias is negative will tend to disappear quickly and sometimes turn into losses so it is usually best to take gains early and/or set trailing stops. Similarly, being short VXX when its Bias is positive and MACD is negative will not produce consistently good results.

Performance Testing
We previously outlined the performance of the WRY-10SMA strategy in this post. The new backtested performance is as follows:

A) Negative WRY MACD, 2013 (Link to Data)


Cumulative Return Jan 1, 2013 - Dec 31, 2013
  • XIV: +107%
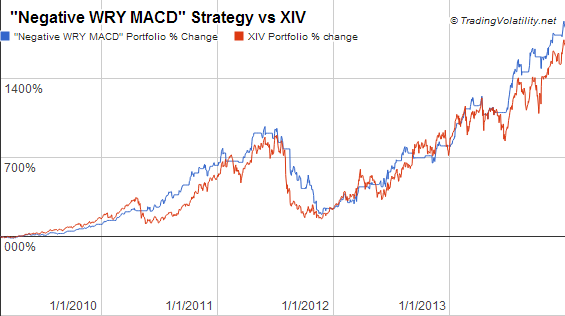
  • "Negative WRY MACD": +141%
"Negative WRY MACD" Trade Summary, 2013 
  • # of Gains: 9
  • # of Losses: 5
  • Avg Return: +6.9%
  • Max Gain: +36.0%
  • Max Loss: -6.5%

For the period 2009-2013 the results for the new strategy did not change much versus the WRY-10SMA strategy. Note the undesirable drawdown in the 2nd half of 2011 when trading against a positive VXX Bias. (Link to Data)


B) Positive WRY MACD, 2013


"Positive WRY MACD" Trade Summary, 2013
  • # of Gains: 5 
  • # of Losses: 9 
  • Avg Return: -0.8% 
  • Max Gain: +11.0% 
  • Max Loss: -11.5%


Full data links of backtested results:
Old: WRY 10SMA, 2013 Performance
New: WRY MACD, 2013 Performance

Old: WRY 10SMA, 2009-2013 Performance
New: WRY MACD, 2009-2013 Performance

------------
Hypothetical and Simulated Performance Disclaimer
The results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown. Additional performance differences in backtests arise from the methodology of using the 4:00pm ET closing values for XIV, VXX, and ZIV as an approximated trade prices for indicators that require VIX and VIX futures to settle at 4:15pm ET.


. . . . . . . . . . . . . .

Stay up to date by having posts sent directly to your RSS feed or Email.